A single employee earning $80,000 on a high-deductible health plan (HDHP) with $4,000 in reserves faces a clear open-enrollment math problem. One major diagnosis can trigger up to $8,500 in 2026 or $8,700 in 2027 out-of-pocket medical bills.
Critical illness insurance (CII) solves that cash crunch by paying a tax-free lump sum directly to the policyholder after a qualifying diagnosis. Unlike traditional health coverage, it imposes no restrictions on spending the payout toward deductibles, rent, or missed wages.
For an HDHP worker with under $5,000 saved, CII works strictly as a 12-to-24-month bridge until reserves match the plan cap. Once an HSA and emergency fund reach $8,700, rising age-banded premiums make self-insuring the better deal.
Why an HDHP Employee With Under $5,000 Faces a Two-Layer Cash Gap
Under IRS HDHP rules for 2026, self-only plans require at least a $1,700 deductible and cap out-of-pocket spending at $8,500 ($3,400 and $17,000 for families). Standard 2026 ACA Marketplace plans cap in-network costs at $10,600 individual and $21,200 family.
For 2027, IRS inflation adjustments raise self-only HDHP minimums to $1,750 and maximum out-of-pocket limits to $8,700 ($3,500 and $17,400 family). An employee holding $3,500 in checking and $500 in an HSA enters 2027 with a $4,700 unfunded gap.
A late-year diagnosis creates a double-reset trap across two consecutive plan years. Hitting the $8,700 cap in December and again in January exposes a single enrollee to $17,400 in medical cost-sharing over two months, plus any unpaid leave.
According to the CFPB medical debt report, high cost-sharing routinely pushes insured households into collections. Although the three credit bureaus voluntarily exclude paid medical collections and balances under $500, larger unpaid hospital bills still risk collections and legal action.
Individual shoppers without employer coverage can review ACA Marketplace options on HealthCare.gov between November 1 and January 15. Starting in 2026, IRS HSA expansion guidance treats all Bronze and Catastrophic plans as HSA-compatible, and buying CII never blocks HSA eligibility.
How Critical Illness Contracts Differ From ACA Medical Plans
Traditional health insurance pays doctors and hospitals for medically necessary care under federal consumer protections. By contrast, CII operates as an independent excepted benefit exempt from Affordable Care Act (ACA) mandates and never coordinates with medical claims.
Most workplace and individual CII policies pay a $10,000 to $50,000 lump sum upon first diagnosis of a covered event. Broad CII outperforms cancer-only policies by covering multiple catastrophic conditions instead of betting on one illness.
- Invasive cancer (typically excluding non-melanoma skin cancer)
- Heart attack (myocardial infarction) meeting strict enzyme and EKG criteria
- Stroke causing lasting neurological deficits
- End-stage kidney (renal) failure
- Major organ transplant or coronary artery bypass surgery
Because CII relies on strict contract language rather than comprehensive medical rules, four clauses routinely shrink or deny claims even after an emergency room visit:
- Narrow clinical definitions: Non-invasive cancers such as carcinoma in situ often pay 10% to 25% of the benefit or nothing, and minor cardiac events without specific biomarker thresholds are excluded.
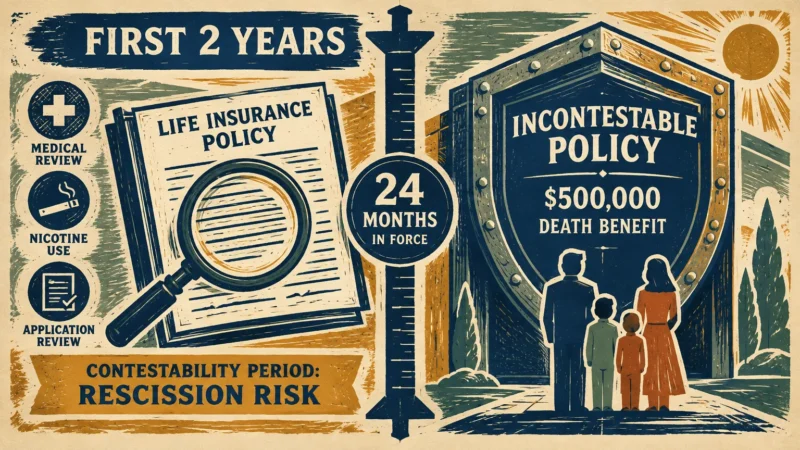
- Waiting and survival windows: Policies commonly enforce a 30-to-90-day waiting period after enrollment and require surviving 14 to 30 days post-diagnosis to collect.
- Age-based benefit cuts: Many employer and individual contracts automatically reduce the lump-sum face value by 50% at age 65 or 70.
- Pre-existing exclusions: Individual applicants undergo screening through medical records and MIB, Inc. underwriting reports, leading to exclusions or denials for prior conditions.
Requesting an MIB file before applying for individual coverage prevents surprises from old chart entries. Group workplace policies offered during open enrollment often waive medical questions up to guaranteed-issue limits, making them easier to secure as a short-term bridge.
The 2027 Open-Enrollment Math: CII Bridge vs. Maxing Your HSA
Running the high-deductible health plan math shows how tax-advantaged savings shrink the $4,700 gap faster than supplemental premiums. In 2026, single filers earning $80,000 subtract a $16,100 standard deduction for $63,900 taxable income, placing them in the 22% federal bracket ($50,400 to $105,700).
For 2027, the IRS announced a $16,600 single standard deduction, leaving $63,400 in taxable income inside the 22% bracket ($52,025 to $109,125). Leveraging an HSA’s triple tax advantage via payroll deduction avoids both 22% income tax and 7.65% FICA tax.
Maxing the $4,500 self-only HSA limit for 2027 ($375 per month, up from $4,400 in 2026) saves $1,334.25 in combined federal taxes for that $80,000 earner. Net paycheck cost is just $3,165.75, while reserves climb from $4,000 to $8,500 by December 2027.
| 2027 Decision Factor ($80,000 Single Earner) | Self-Only HDHP Baseline | Max 2027 HSA via Payroll | Employer CII Bridge Policy |
|---|---|---|---|
| 2027 statutory limit or typical benefit | $1,750 min deductible; $8,700 max OOP (IRS Rev. Proc. 2026-24) | $4,500 annual contribution limit ($9,000 family) | $10,000 to $50,000 lump sum; no ACA cap |
| Federal tax impact (22% bracket + 7.65% FICA) | Section 125 medical premiums stay pre-tax | Saves $1,334.25 in federal income and FICA taxes | After-tax premiums yield tax-free payout (IRS Pub. 525) |
| Trigger required to access funds | In-network covered medical claims | Any qualified medical expense or post-65 withdrawal | Strict policy diagnosis (excludes minor or unlisted events) |
| Unspent balance at year-end | Annual out-of-pocket cap resets January 1 | 100% rolls over and grows tax-free | $0 refunded; premiums rise in 5-year age bands |
| Effect on $4,700 gap ($8,700 minus $4,000) | Leaves $4,700 exposed in Year 1 | Reaches $8,500 total reserves by December 2027 | Covers gap immediately during 12-to-24-month bridge |
That $8,500 year-end balance puts the employee $200 shy of self-insuring the full 2027 HDHP cap in twelve months. Adding a low-cost workplace CII policy only protects against an early-year diagnosis before those monthly HSA deposits accumulate.
Holding CII past that break-even point destroys value because premiums climb sharply with age. An illustrative $20,000 workplace policy costing $22 monthly at age 35 ($2,640 over ten level years) commonly jumps across five-year age bands toward $85 monthly by age 55.
At $85 a month, ten years of premiums total $10,200—over half the $20,000 face value—with nothing returned if no listed illness occurs. Dropping CII once liquid reserves equal $8,700 frees every future premium dollar for permanent, flexible savings.
Disability Coverage, Tax Traps, and Your Open-Enrollment Checklist
Before adding CII to an HDHP election, compare it against disability insurance that protects your paycheck. Long-term disability (LTD) replaces monthly income for any disabling condition, including musculoskeletal injuries and mental health disorders that CII contracts exclude.
Because employer LTD plans often enforce a 90-day waiting period, modest CII works best as a short bridge when savings sit below $5,000. Once reserves cover 90 days of bills plus $8,700, LTD and an HSA outperform CII.
Payroll tax treatment also determines how much cash reaches a policyholder’s bank account. Under IRS Publication 525 rules, CII payouts are tax-free only when paid with after-tax dollars, whereas employer-paid or pre-tax premiums make the lump sum taxable income.
Holding multiple CII policies is legal, and each indemnity contract pays independently, though duplicate premiums rarely beat funding an HSA. Follow these four verification steps with your employer and regulators before open enrollment closes:
- Pull your Summary of Benefits and Coverage (SBC): Confirm your exact 2027 in-network out-of-pocket maximum on your employer benefits portal or during the November 1 to January 15 HealthCare.gov window, and calculate your shortfall against current savings.
- Elect Section 125 HSA payroll contributions: Set your 2027 HSA election up to $4,500 self-only ($375 monthly) through payroll rather than a personal bank transfer so contributions avoid both federal income and FICA taxes.
- Demand the CII group certificate and tax method: Ask your HR benefits administrator for the full certificate of insurance—not the summary flyer—to verify waiting periods, age-65 reductions, and after-tax payroll coding.
- Know who regulates and resolves disputes: Contact the U.S. Department of Labor Employee Benefits Security Administration (EBSA) for employer ERISA disclosure rules, your state department of insurance for policy terms and rate oversight, or a CPA or Enrolled Agent for IRS Publication 525 tax reporting.