
You probably noticed your car insurance premium took a significant jump over the last year. If it feels like the numbers on your renewal notice are disconnected from your actual driving habits, you are witnessing a fundamental shift in how the insurance industry assesses risk. In 2025, insurers have moved far beyond the simple “age and driving record” model of the past. They now employ sophisticated machine-learning algorithms that process thousands of data points to predict the likelihood of you filing a claim.
While general inflation has cooled in other sectors, the cost of car insurance continues to outpace the Consumer Price Index. According to data from the Bureau of Labor Statistics, motor vehicle insurance costs have risen at a rate significantly higher than the average for all items. This spike stems from a “perfect storm” of rising repair costs, more frequent natural disasters, and a surge in the severity of accidents. Understanding how auto rates are calculated is no longer just a matter of curiosity; it is a financial necessity if you want to keep your monthly budget under control.
1. Your Driving Record and the Rise of Telematics
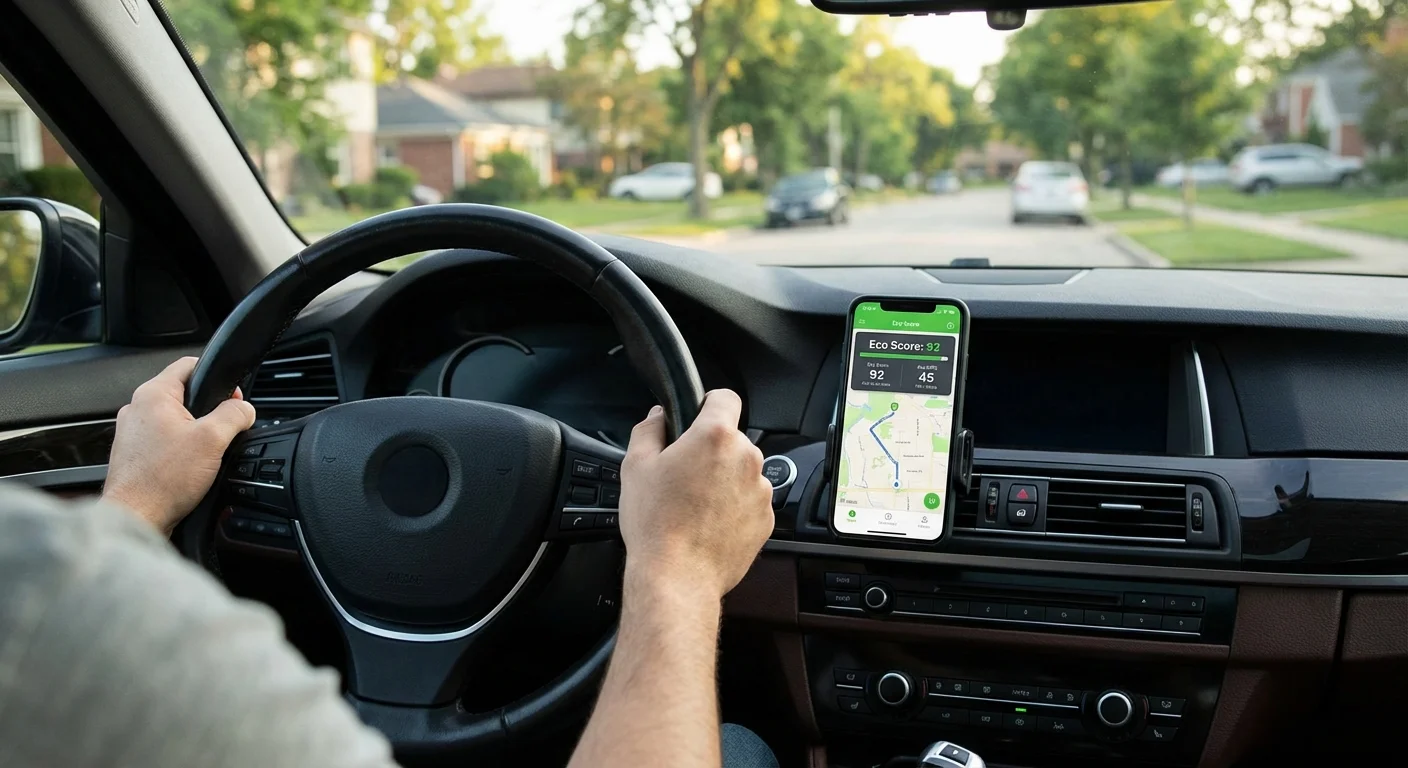
Your driving history remains the most influential factor in your insurance premium, but the way insurers “watch” you has changed. Traditionally, an insurance company only looked at your “MVR” or Motor Vehicle Record. If you had a clean slate with no speeding tickets or at-fault accidents for three to five years, you received the best rates. While that still matters, 2025 is the year of the telematics-first policy.
Telematics programs—often marketed as “Usage-Based Insurance” (UBI)—track your real-time behavior via a smartphone app or a device plugged into your car’s ODB-II port. Insurers now monitor how hard you brake, how fast you accelerate, whether you use your phone while driving, and even what time of day you are on the road. If you drive 2,000 miles a month during late-night hours, your risk profile looks vastly different to an insurer than someone who drives 500 miles a month during daylight. This shift allows for more personalized pricing, but it also means that “hidden” habits could be driving your rates up without you realizing it.
To use this to your advantage, you should consider a telematics program only if you are a conservative driver with a short commute. Many carriers now offer an immediate “participation discount” of 10% just for signing up, with potential savings of up to 40% for the safest drivers. However, be aware that some companies have transitioned from “discount-only” models to “surcharge” models, where poor telematics data can actually increase your premium.
2. Credit-Based Insurance Scores
In most states, your credit history has a massive impact on your car insurance factors. Except in states like California, Hawaii, Massachusetts, and Michigan—where the practice is restricted or banned—insurers use a “Credit-Based Insurance Score” to determine your premium. This is not the same as your FICO score used for mortgages, but it relies on the same data provided by credit bureaus.
Statistically, insurers have found a strong correlation between credit management and insurance risk. Actuarial data suggests that drivers with lower credit scores are more likely to file claims and, more importantly, those claims tend to be more expensive. If you have a “Poor” credit score, you might pay double the premium of a driver with an “Excellent” score, even if both of you have identical driving records.
“Your credit score is a reflection of how you handle your life. If you’re responsible with your money, you’re likely to be responsible behind the wheel.” — Suze Orman, Personal Finance Expert
Improving your credit score is one of the most effective long-term strategies for lowering car insurance. You can monitor your credit report for free via the Consumer Financial Protection Bureau (CFPB) resources to ensure no errors are dragging your score down. Even a modest move from the “Fair” category to “Good” can save you hundreds of dollars per year on premiums.
3. Vehicle Technology and Repair Complexity
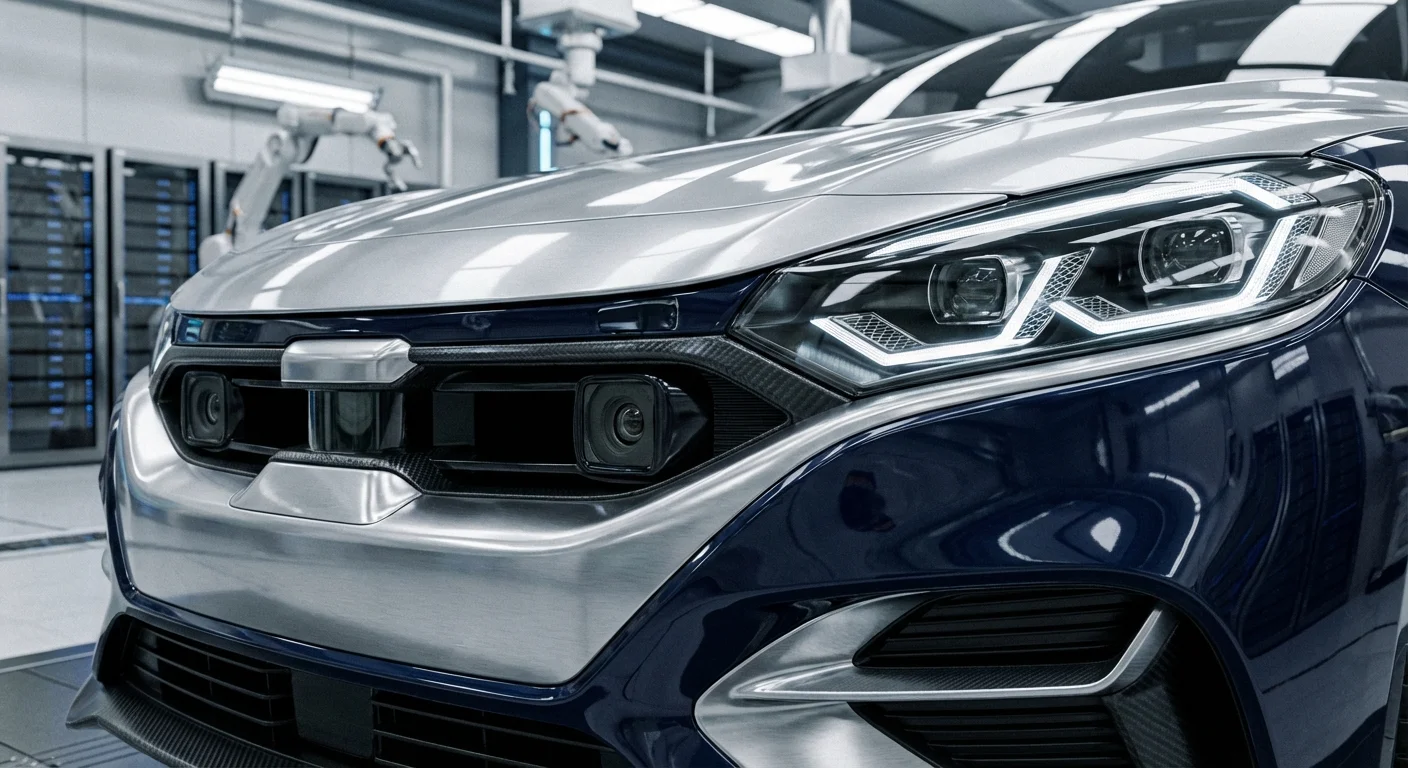
What you drive matters more in 2025 than it did a decade ago because cars have become essentially “computers on wheels.” While features like Automatic Emergency Braking (AEB) and Lane Departure Warning reduce the frequency of accidents, they have exponentially increased the cost of repairs. This phenomenon is often referred to as “Social Inflation” within the industry.
In the past, a minor “fender bender” required a new piece of plastic and some paint. Today, that same bumper contains ultrasonic sensors, cameras, and radar units that require expensive recalibration. If you drive an Electric Vehicle (EV), your premium reflects even higher risks; EV repairs are roughly 25% to 50% more expensive than internal combustion engine vehicles, primarily due to the specialized labor required and the high cost of battery components.
Before purchasing a new vehicle, you should get an insurance quote for the specific VIN. Don’t assume a “safe” car is a “cheap to insure” car. Some vehicles with high theft rates—specifically certain older models that lack modern engine immobilizers—have seen astronomical rate hikes or even outright denials of coverage from major carriers in certain regions.
4. Geographic Location and Climate Risk
Your ZIP code has always influenced your rate, but insurers are now using more granular data to assess environmental risks. In 2025, location-based rating includes more than just local crime rates or traffic density; it factors in “catastrophic loss” data related to climate change. If you live in an area prone to wildfires, hurricanes, or even severe hailstorms, you are likely paying a “climate surcharge” on your comprehensive coverage.
The Federal Trade Commission (FTC) and state insurance commissioners have noted that as reinsurance rates (insurance for insurance companies) rise due to global disasters, those costs are passed directly to you. Even if you haven’t moved or filed a claim, your rates may spike because your neighbors have filed claims for flood or wind damage. This makes shopping around every 12 months essential, as different companies have different “appetites” for risk in specific geographic zones.
| Location Factor | Impact on Rate | Reasoning |
|---|---|---|
| Urban/City Centers | High Increase | Higher density of accidents, theft, and vandalism. |
| Coastal/Wildfire Zones | Moderate to High | Risk of total loss due to environmental catastrophes. |
| Rural Areas | Decrease | Lower traffic volume and reduced collision frequency. |
5. Coverage Levels and Deductible Choice
The final factor—and the one you have the most direct control over—is the structure of your policy. Your coverage limits (the maximum an insurer will pay) and your deductible (the amount you pay out of pocket before insurance kicks in) create a mathematical balance of risk. In 2025, the “standard” 100/300/100 coverage (meaning $100,000 for injuries per person, $300,000 per accident, and $100,000 for property damage) is increasingly viewed as the minimum necessary for the average driver, given that a single high-end EV can easily cost $80,000 to replace.
Choosing a higher deductible is a powerful tool for lowering car insurance premiums. Moving from a $250 deductible to a $1,000 deductible can reduce your collision and comprehensive premiums by 15% to 30%. However, you must ensure you have that $1,000 tucked away in an emergency fund. If an accident happens and you cannot afford your deductible, your car may sit in a repair shop indefinitely.
Furthermore, insurers look at your “insurance tenure” and “loyalty.” Ironically, being a loyal customer for 20 years can sometimes lead to “price optimization,” where an insurer slowly raises your rates because they assume you won’t bother to switch. This is why comparing quotes from at least three different companies every year is the most effective way to ensure your coverage levels align with market pricing.
Pitfalls to Watch For
When you are trying to lower your insurance costs, it is easy to make mistakes that leave you financially vulnerable. One of the most common pitfalls is “underinsuring” your liability. In an era of record-high medical costs and expensive vehicle replacements, carrying only the state-minimum liability limits can lead to a lawsuit that targets your personal assets or future wages if you cause a major accident.
Another common mistake is failing to update your “annual mileage” with your insurer. If you transitioned to a remote or hybrid work schedule but your policy still lists a 40-mile daily commute, you are overpaying. Conversely, if you started driving for a ride-sharing service like Uber or Lyft without a “rideshare endorsement,” your insurer can legally deny any claim you make while the app is on, even if you don’t have a passenger in the car.
Finally, watch out for the “lapsed coverage” trap. Even a one-day gap in your insurance history can categorize you as a “high-risk” driver for the next six months to a year. If you are selling your car and plan to buy a new one in a month, look into a “non-owner’s policy” to maintain continuous coverage and keep your future rates low.
Getting Expert Help
Navigating the complex world of modern insurance can be overwhelming. While online quotes are convenient, there are specific scenarios where you should consult an independent insurance agent:
- You have a teenager heading to college: Adding a teen driver is incredibly expensive, but an expert can help you navigate “distant student” discounts or “good student” certifications that an automated system might overlook.
- You own significant assets: If your net worth exceeds your insurance limits, an agent can help you set up an “Umbrella Policy,” which provides an extra layer of liability protection across both your home and auto insurance.
- You have a “complicated” driving history: If you have an SR-22 requirement or multiple accidents, an independent agent can access “surplus lines” carriers that specialize in high-risk drivers and don’t market directly to the public.
- You want to bundle multiple types of risk: Bundling home, auto, and life insurance is the oldest trick in the book for a reason—it works. An expert can calculate whether the bundle discount outweighs the benefit of having separate, specialized policies.
Frequently Asked Questions
Does my marital status really affect my car insurance rate?
Yes. Statistically, married drivers are involved in fewer accidents and file fewer claims than single, divorced, or widowed drivers. Insurers view marriage as a sign of stability, and being part of a multi-car household often qualifies you for further discounts.
Will my insurance go down when I turn 25?
While 25 is the traditional age for a rate drop, it isn’t a magic number. Your rate will decrease gradually every year you maintain a clean record. However, if you are 25 with a recent speeding ticket and poor credit, you will still pay more than a 22-year-old with a perfect record and great credit.
Can I lower my rate by taking a defensive driving course?
In many states, completing an accredited defensive driving or “accident prevention” course guarantees a discount for three years. This is especially helpful for drivers under 25 or over 65. You can find approved courses through your state’s DMV or organizations like The National Safety Council.
Do insurance companies track where I drive with GPS?
Only if you opt into a telematics program. Standard policies do not track your location. If you do choose a telematics app, the insurer typically uses GPS data to determine the “riskiness” of your routes (e.g., high-crime areas or accident-prone intersections), but they are legally required to disclose what data they collect in their privacy policy.
The landscape of auto insurance in 2025 is more data-driven than ever before. While factors like repair costs and climate change are outside your control, you still hold the most important levers: your driving behavior, your credit health, and your willingness to shop for a better deal. Take an hour this week to review your current policy declarations page. If you haven’t compared rates in the last 12 months, you are likely leaving money on the table.
The information in this guide is meant for educational purposes. Your specific circumstances—including income, debt, tax situation, and goals—may require different approaches. When in doubt, consult a licensed professional.
Last updated: February 2026. Financial regulations and rates change frequently—verify current details with official sources.
Leave a Reply