LGBTQ+ households building a family face sharply different federal tax rules depending on their path. For 2026, adoption qualifies for up to $17,670 per child in federal tax credits and $17,670 in tax-free employer assistance, while gestational surrogacy receives neither benefit.
Planning around those rules requires coordinating liquid cash reserves, workplace benefits, medical deductions, and legal safeguards before signing an agency or clinic contract. Knowing which costs qualify for tax relief and which require after-tax savings determines how much cash you must accumulate.
Comparing Adoption and Gestational Surrogacy Tax Rules
Federal tax law separates family-building expenses into two distinct categories. Adoption triggers dedicated credits and income exclusions, whereas assisted reproduction relies on narrow medical expense rules that exclude third-party surrogates and egg donors.
Because domestic adoption, international adoption, and gestational surrogacy follow different payment schedules and tax timelines, comparing the rules side by side prevents cash-flow surprises.
| Tax or Financial Rule | Domestic Adoption | International Adoption | Gestational Surrogacy |
|---|---|---|---|
| 2026 Adoption Credit (Form 8839) | Up to $17,670 per child | Up to $17,670 per child | Not eligible |
| 2026 Refundable Portion | Up to $5,120 per child | Up to $5,120 per child | Not eligible |
| 2027 Announced Credit / Refundable Cap | $18,250 max / $5,280 refundable | $18,250 max / $5,280 refundable | Not eligible |
| MAGI Phase-Out Range (2026 / 2027) | $265,080 to $305,080 / $273,680 to $313,680 | $265,080 to $305,080 / $273,680 to $313,680 | Not applicable |
| Tax-Free Employer Adoption Exclusion (2026 / 2027) | $17,670 / $18,250 | $17,670 / $18,250 | No federal exclusion |
| Schedule A Medical Deduction | Not eligible | Not eligible | Own-body IVF only; third-party fees disallowed |
| When Credit Can Be Claimed | Year after payment, or year finalized | Only in or after year finalized | Not applicable |
2026–2027 Refundable Adoption Credit Caps and Domestic Timing
On IRS Form 8839, the federal Adoption Tax Credit reaches $17,670 per eligible child for 2026, up from $17,280 in 2025. Under Public Law 119-21, enacted in July 2025, the credit became partially refundable rather than strictly nonrefundable.
Up to $5,120 per child is refundable in 2026, meaning you can receive that portion as a tax refund even if you owe zero federal income tax. Any remaining unused nonrefundable credit carries forward for up to five tax years.
For 2027, the IRS announced the maximum Adoption Tax Credit rises to $18,250 per child, with up to $5,280 refundable. The credit phases out between $265,080 and $305,080 MAGI in 2026, and $273,680 to $313,680 in 2027.
Under IRS qualified adoption expense rules, eligible costs include reasonable and necessary adoption fees, court costs, attorney fees, home study charges, and required travel. Timing rules differ depending on whether you adopt domestically or internationally.
In a domestic adoption, you can claim qualified expenses paid before finalization in the tax year after you pay them, even if the adoption never finalizes. In a foreign adoption, you cannot claim any expenses until the tax year the adoption becomes final.
Combining Employer Adoption Benefits With Form 8839: A 2026 Example
Many employers reimburse adoption or fertility costs through workplace benefit portals. Up to $17,670 in qualified employer-provided adoption assistance is excluded from your federal taxable income in 2026, rising to an announced $18,250 for 2027.
Employers report this benefit in Box 12 of Form W-2 using Code T, and the same MAGI phase-out limits apply. Although excluded from federal income tax, employer adoption assistance remains subject to Social Security, Medicare, and federal unemployment payroll taxes.
You cannot claim both the income exclusion and the Adoption Tax Credit on the same dollar of expenses. However, if total qualified costs exceed your employer benefit, Form 8839 Part III requires applying the exclusion first and claiming the credit on the remaining expenses.
A married couple filing jointly in 2026 has $220,000 in total income including a $15,000 employer adoption benefit, keeping their MAGI below the $265,080 phase-out threshold. They finalize a domestic adoption costing $38,000 in qualified expenses.
Subtracting the $15,000 employer benefit leaves $23,000 in out-of-pocket qualified expenses, allowing them to claim the full $17,670 Adoption Tax Credit. After the $32,200 standard deduction and $15,000 exclusion, their 2026 taxable income drops from $187,800 to $172,800.
In the 22% marginal bracket, the $15,000 exclusion saves $3,300 in federal income tax, reducing tax before credits from $30,740 to $27,440. Applying the $17,670 credit ($5,120 refundable and $12,550 nonrefundable) cuts their final federal income tax bill to $9,770, saving $20,970 overall.
Why Fertility and Surrogacy Costs Face Stricter Tax Limits
Gestational surrogacy involves major expense categories that do not qualify for Form 8839. Typical outlays include agency coordination retainers, carrier compensation, fertility clinic and pharmacy bills, specialized maternity insurance if the carrier’s policy excludes surrogacy, escrow administration fees, and legal parentage orders.
Instead of a tax credit, intended parents look to itemized medical deductions under IRS Publication 502. Medical care expenses for yourself, your spouse, or a dependent are deductible on Schedule A only to the extent they exceed 7.5% of your adjusted gross income.
Fertility enhancement procedures such as in vitro fertilization (IVF) and temporary egg or sperm storage qualify when performed on your own body or your spouse’s body. However, those rules rarely cover third-party reproduction costs.
In IRS Private Letter Ruling 202114001, citing Morrissey v. United States, the IRS ruled that a married same-sex couple could not deduct egg donation or gestational surrogacy costs under IRC Section 213. Because the procedures occurred on third parties, they were disallowed.
If you are enrolled in an eligible high-deductible health plan, a Health Savings Account (HSA) can still shelter qualified medical costs performed on your own body. Contribution limits are $4,400 self-only or $8,750 family in 2026, rising to an announced $4,500 and $9,000 for 2027.
Workplace Leave, Grants, and Cash Reserves
Outside the tax code, employer fertility benefits, nonprofit grants, and job-protected leave can offset substantial upfront cash needs. Verifying these options before signing contracts helps you avoid high-interest personal debt or early retirement withdrawals.
- Employer fertility stipends: Some workplace plans reimburse IVF, egg donation, or surrogacy fees up to a set lifetime cap, though unlike qualified adoption assistance, surrogacy reimbursements are generally treated as taxable wages.
- LGBTQ+ family-building grants: Family Equality’s grant directory tracks adoption grants, assisted reproduction awards, and fertility medication discounts, while national nonprofits such as HelpUsAdopt.org offer adoption grants up to $30,000 paid directly to licensed agencies or attorneys.
- Job-protected bonding leave: Under U.S. Department of Labor Fact Sheet #28B, eligible workers can take up to 12 workweeks of unpaid, job-protected FMLA leave on an in loco parentis basis, protecting non-biological and non-legal LGBTQ+ co-parents who assume parental responsibilities.
Keep money needed for upcoming agency retainers, home studies, or escrow accounts in liquid cash rather than stocks or long-term CDs. Placing those deposits in a high-yield savings account preserves principal while keeping funds accessible for sudden invoice deadlines.
Also fund a separate post-placement reserve before your final agency or clinic payment leaves your account. Planning early for first-year baby expenses such as childcare, pediatric co-pays, and gear prevents cash shortfalls during unpaid leave.
Legal Protections and Insurance Updates After Placement
Parental rights for non-biological parents can still face legal challenges across state or international borders even when both spouses appear on a birth certificate. Budgeting for a second-parent or confirmatory adoption provides a court judgment recognized nationwide under the U.S. Constitution.
Without a formal court order, a non-biological parent may encounter obstacles claiming Social Security survivor benefits, health insurance coverage, or inheritance rights for the child. Before escrow accounts are funded or contracts signed, review your legal steps carefully.
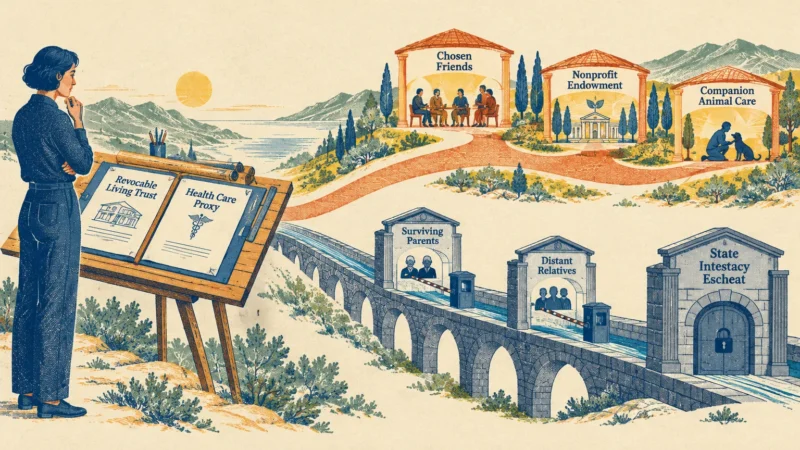
Update your will, guardianship designations, and powers of attorney as soon as placement begins. If you take on debt or spend down cash reserves, re-evaluate term life insurance so either parent can cover housing and childcare costs alone.
Have a family-law or assisted-reproduction attorney map out confirmatory-adoption court filings and verify escrow bonding before you sign contracts or wire deposits. A CPA or enrolled agent can coordinate Form 8839 benefit ordering and Schedule A medical claims across tax years.
Can retirement or HSA contributions help you qualify under the MAGI phase-out?
Yes, because pre-tax 401(k), 403(b), and HSA contributions lower your Adjusted Gross Income and MAGI. In 2026, employees can defer up to $24,500 into a 401(k), rising to an announced $25,500 for 2027, helping households near the $265,080 threshold preserve more credit.