Section editor · 26 guides
Andreea Cibotariu
Edits Insurance: health, auto, home and renters, life and disability coverage. Checks plan rules, enrollment windows and consumer protections against HealthCare.gov, the Department of Labor and state insurance department pages, and says plainly where a state's rules differ.
 Latest guide
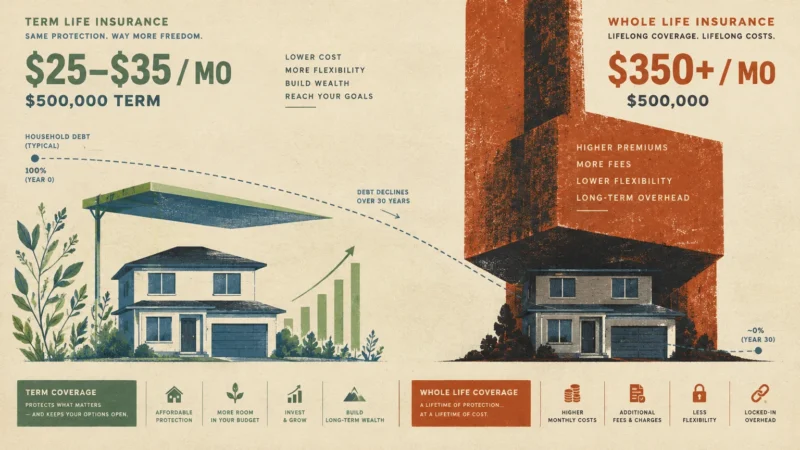
Term Life Insurance vs. Whole Life: Which is Best for Young Adults?
Guides edited by Andreea Cibotariu
Newest first-
 Critical Illness Insurance vs. Traditional Health Plans: Do You Really Need Both?
Compare critical illness insurance with 2026 HDHP ($8,500/$17,000) and ACA ($10,600/$21,200) caps, tax rules, and breakeven math to decide if you need both.
-
 Insurance for E-bikes and Scooters: Is it Covered by Your Homeowners Policy?
Standard homeowners and renters policies often exclude motorized e-bikes and scooters. See how class rules, sublimits, and standalone coverage compare.
-
 Long-Term Care Insurance: When is the ‘Sweet Spot’ Age to Buy a Policy?
Compare your 50s vs. 60s for buying long-term care insurance using 2026 CareScout care costs, Medicare limits, Medicaid look-back rules, and IRS tax caps.
-
 The High-Deductible Health Plan (HDHP) Math: When Is It the Right Choice?
Compare an HDHP and PPO using 2026 and 2027 IRS limits, payroll tax savings, employer HSA seeds, and total net cost across three medical spend scenarios.
-
 Usage-Based Auto Insurance: Can a Driving Tracker App Actually Lower Your Rates?
Compare usage-based auto insurance programs, pay-per-mile math, state surcharge rules, and connected-car data privacy risks before enrolling in a tracker.
-
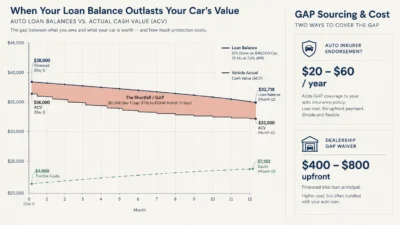 GAP Insurance: Does Your Auto Policy Cover Your Loan Balance if You Total Your Car?
Compare GAP insurance from auto insurers ($20-$60/yr) vs. dealers ($400-$800), see year-one underwater loan math, and check exclusions before buying.
-
 Loss of Use Coverage: What Happens if Your Home is Uninhabitable After a Claim?
Coverage D (Loss of Use) pays extra housing and meal costs if your home is uninhabitable. See how ALE limits, utility offsets, and IRC 123 tax…
-
 Valuable Personal Property Endorsements: Insuring Jewelry, Art, and High-End Tech
Standard homeowners policies cap jewelry theft at $1,000-$2,000. Compare scheduled endorsements and floaters for rings, art, and high-end tech.
-
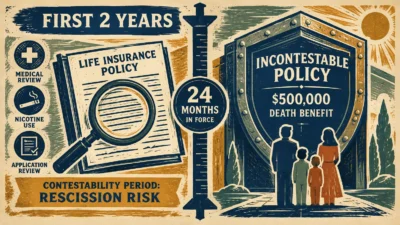 The Incontestability Clause: How it Protects Your Life Insurance Beneficiaries After Two Years
After two years in force, the life insurance incontestability clause bars most claim denials over application errors. See key exceptions and reset rules.
-
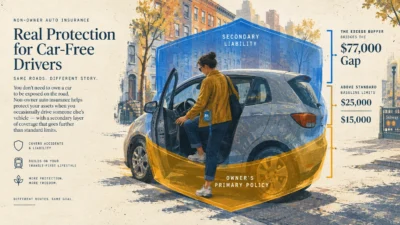 Non-Owner Auto Insurance: Why You Need It Even if You Don’t Own a Vehicle
How non-owner auto insurance provides secondary liability, prevents coverage-gap rate hikes, meets SR-22 rules, and handles rental car exclusions.
-
 Personal Cyber Insurance: Do You Need Protection Against Identity Theft and Phishing?
Compare Regulation E and Z fraud caps against homeowners riders and standalone cyber policies, including wire-scam exclusions and a 4-point buyer checklist.