
The physical act of moving your furniture across a state line is exhausting, but the administrative trail you leave behind can be even more taxing—literally. When you pack your life into a U-Haul and head for a new state, you aren’t just changing your zip code; you are changing your tax jurisdiction. For the year of your move, you likely fall into the category of a part-year resident, a status that requires specific reporting to ensure you don’t pay the same dollar twice to two different governors.
According to the U.S. Census Bureau, millions of Americans move across state lines every year. In 2022 alone, approximately 8.2 million people relocated to a different state. Each of these individuals faced the same puzzle: how to split their income between their old home and their new one. While the federal tax return remains largely the same regardless of where you live, state tax departments are notoriously protective of their revenue. If you don’t clearly define when you left one state and entered another, you risk an audit or unnecessary double taxation.
The Essentials of Part-Year Residency
A part-year resident is exactly what it sounds like: someone who lived in a state for only a portion of the tax year with the intent to make that state their permanent home. This status triggers the requirement to file a “Part-Year Resident” tax return in both your former state and your new state, provided both states collect income tax.
Most states use a specific form for this, often designated with “NR” (Non-Resident) or “PY” (Part-Year). For example, if you move from New York to California, you would file Form IT-203 in New York and Form 540NR in California. The goal of these forms is to “allocate” your income—assigning specific dollars to the state where you earned them or where you lived when you received them.
- Old State: You generally pay taxes on all income earned while you were a resident there, plus any income from sources within that state after you moved.
- New State: You pay taxes on all income earned after you became a resident, regardless of where the employer is located.
- No-Tax States: If you move from or to a state with no income tax (like Texas, Florida, or Washington), your filing burden is cut in half, as you only need to worry about the state that actually collects tax.
The Critical Difference Between Domicile and Residence
Tax departments look at more than just the date you handed over your apartment keys. They look at your “domicile.” While you can have multiple residences, you generally have only one domicile. This is the place you intend to return to and the place you consider your true, permanent home.
Establishing a new domicile is a matter of intent backed by action. If you move to a new state but keep your old driver’s license, stay registered to vote in your former town, and keep your primary bank accounts there, your old state might argue that you never truly left. This is particularly common in high-tax states like New York or Minnesota, which may aggressively pursue former residents who move to low-tax states but maintain significant ties.
“Owning a home is a great investment, but it also anchors you to a specific tax reality. When you move, you must cut the cord cleanly if you want the tax benefits of your new location.” — Suze Orman, Personal Finance Expert
How to Allocate Your Income Correctly
The core of a part-year resident return is income allocation. You must look at every dollar you earned during the year and decide which state has the right to tax it. This is usually broken down into two categories: earned income and unearned income.
Earned Income (Wages and Salaries)
This is usually the simplest part. You look at your pay stubs. Any money earned from January 1 until the day you moved belongs to your old state. Any money earned from your move date until December 31 belongs to your new state. Many employers will split this for you on your W-2, showing “State Wages” for two different states. However, if your employer didn’t update your withholding immediately, you may need to manually calculate these figures based on your move date.
Unearned Income (Interest, Dividends, and Capital Gains)
Unearned income is typically taxed by the state where you were a resident at the time you received the payment. If your bank paid you interest in March and you moved in June, that interest is taxed by your old state. If you sold stock in October, the capital gains are taxed by your new state. This requires a “books-closed” approach where you look at the specific dates of transactions rather than just dividing the annual total by two.
| Income Type | How It Is Usually Allocated | Common Documentation Needed |
|---|---|---|
| W-2 Wages | Based on the physical location where the work was performed. | Final pay stub before the move; W-2 form. |
| Interest/Dividends | Taxed by the state of residency on the date of payout. | Monthly brokerage or bank statements. |
| Rental Income | Always taxed by the state where the property is located. | Schedule E; property records. |
| Capital Gains | Taxed by the state of residency on the date of the sale. | 1099-B form showing transaction dates. |
The Remote Work Complication
If you work remotely, moving states becomes significantly more complex. Some states, most notably New York, follow the “Convenience of the Employer” rule. This rule states that if your employer is based in New York, but you work from home in another state for your own convenience (rather than your employer’s necessity), New York will continue to tax your income as if you were still sitting in an office in Manhattan.
If you move from New York to a state like Connecticut or Pennsylvania, you might find yourself in a tug-of-war. Your new state wants to tax you because you live there, and your old state wants to tax you because your boss is there. Most states offer a “Credit for Taxes Paid to Other States” to prevent double taxation, but the rules are rigid. You generally pay the higher of the two tax rates, and the credit usually applies to the state of residence. You can find more specific guidance on state-to-state tax credits via the IRS guidelines regarding moving and residency.
Creating a Paper Trail for Your Move
The burden of proof for a move rests on your shoulders. If a state tax auditor questions your move date, “I think it was sometime in July” will not suffice. You need to provide concrete evidence of when your residency changed. This is especially vital if you are moving from a high-tax state to a state with no income tax.
To solidify your claim, take the following steps as soon as you arrive in your new state:
- Update your Driver’s License: Do this within 30 days of moving. The date on your new license is a powerful piece of evidence.
- Register to Vote: This is a primary indicator of domicile.
- Change your Mailing Address: Update your address with the USPS and, more importantly, with the IRS using Form 8822.
- Utility Bills: Keep the final bill from your old home and the first bill from your new home. These show exactly when you stopped consuming resources in one place and started in another.
- Update Medical and Legal Records: Register with a new doctor and update your insurance policies to reflect your new address.
Avoiding Common Errors
Filing as a part-year resident is prone to mistakes because it requires more manual entry than a standard return. Software often asks for “Total Income” and then asks you to “Allocate” it. Many taxpayers accidentally double-count their income or fail to account for income that isn’t tied to a paycheck.
The “Whole-Year” Mistake: Do not accidentally file as a full-year resident in both states. This is a common error when people use basic tax software and don’t read the residency questions carefully. If you do this, both states will try to tax 100% of your annual income, and you will be stuck waiting months for a refund after filing an amended return.
Forgetting Reciprocity Agreements: Some neighboring states (like Virginia and Maryland or Illinois and Iowa) have reciprocity agreements. These agreements allow residents of one state to work in the other without filing a non-resident return. If you move between states with reciprocity, your tax situation might be simpler than the standard part-year resident rules suggest.
Ignoring State-Specific Credits: Many people forget to claim the credit for taxes paid to other states. If you earned $50,000 in State A and paid $2,000 in tax, then moved to State B, State B might also want to tax that $50,000. However, State B will usually give you a credit for the $2,000 you already paid to State A. If you don’t claim this credit, you are effectively donating money to the government.
When DIY Isn’t Enough
While many part-year moves are straightforward, certain scenarios demand professional help from a CPA or an Enrolled Agent. Managing multiple state filings is a primary reason why many taxpayers seek professional assistance, as noted by the Consumer Financial Protection Bureau in their educational resources on financial readiness.
Consider hiring a professional if:
- You own a business or are a partner in an LLC: Business income often follows “nexus” rules that are much more complicated than W-2 income.
- You moved to or from a “Convenience of the Employer” state: States like New York, Delaware, and Nebraska have aggressive rules that can result in complex double-taxation scenarios.
- You have significant equity compensation: If you had stock options that vested or were exercised during the year of your move, determining which state gets to tax that “wealth” can involve complex vesting-period calculations.
- You moved mid-month and have complex investments: Manually pro-rating interest, dividends, and capital gains requires meticulous record-keeping that tax pros are better equipped to handle.
Practical Steps to Take Right Now
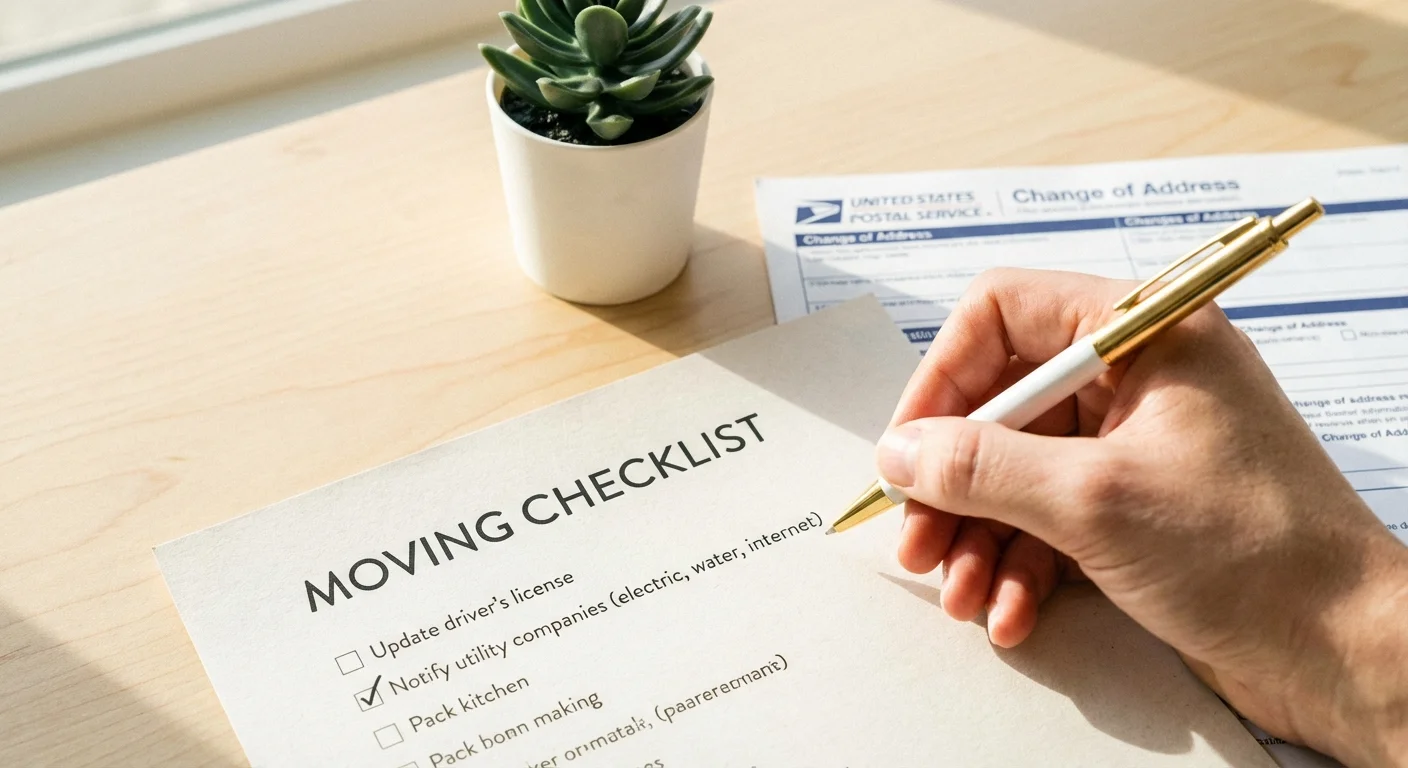
If you are in the middle of a move or have recently completed one, don’t wait until April to gather your documents. Your first step is to create a “Tax Move Folder.” Inside, place your closing disclosure or lease agreement, your moving truck receipts, and your new voter registration card.
Next, check your pay stubs. If your employer is still withholding tax for your old state, notify your HR department immediately. They need to update your “SIT” (State Income Tax) withholding to your new state. If they don’t, you’ll end up owing a large sum to your new state while waiting for a large refund from your old one—a cash flow nightmare you want to avoid.
Finally, research the specific tax forms for both states. Visit the official Department of Revenue websites for both your old and new homes. Most states provide a “Part-Year Resident Guide” that explains exactly which lines to fill out on their specific forms. Being proactive now will save you hours of frustration when tax season arrives.
This article provides general financial education and information only. Everyone’s financial situation is unique—what works for others may not work for you. For personalized advice, consider consulting a qualified financial professional such as a CFP or CPA.
Last updated: February 2026. Financial regulations and rates change frequently—verify current details with official sources.
Leave a Reply