
You probably know the feeling of buying one new item only to realize that everything else you own suddenly looks shabby by comparison. Perhaps you bought a sleek, modern sofa, and now your old coffee table looks like a relic from a college dormitory. Two weeks later, you find yourself browsing for a new rug, then floor lamps, and eventually, you are repainting the entire living room to match a single piece of furniture. This isn’t just a streak of bad luck or a sudden burst of inspiration; you are experiencing a psychological phenomenon known as the Diderot Effect.
The Diderot Effect describes a social phenomenon related to consumer goods that creates a spiral of consumption. It suggests that obtaining a new possession often creates a spiral of dissatisfaction with your current belongings, leading you to purchase even more items to create a cohesive “set.” This mindset can wreak havoc on your budget, turning a single $50 purchase into a $500 spending spree before you even realize what happened.
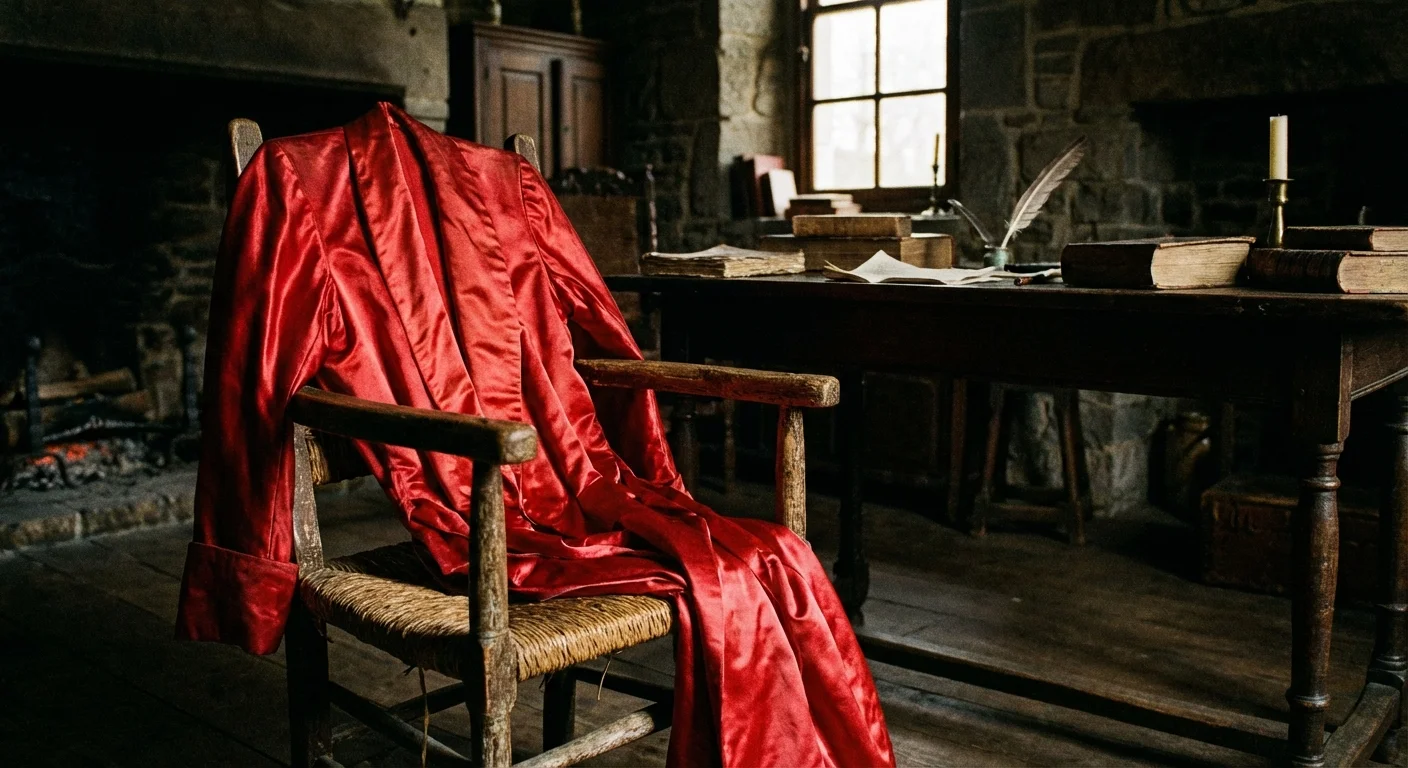
The Scarlet Robe That Ruined a Philosopher
The term originates from an 18th-century French philosopher named Denis Diderot. For most of his life, Diderot lived in relative poverty—until the Empress of Russia, Catherine the Great, heard of his financial struggles and purchased his library for a massive sum. Suddenly wealthy, Diderot treated himself to a beautiful, scarlet silk dressing robe.
Initially, he felt magnificent. However, the beauty of the robe soon became a burden. As he sat in his study, he noticed that his old straw chair looked pathetic next to the silk. He replaced the chair. Then, his old wooden desk seemed out of place, so he bought a new, expensive one. One by one, he replaced his rugs, his wall hangings, and his bookshelves to match the elegance of the robe. Eventually, he found himself surrounded by luxury but drowning in debt and regret. He wrote about this experience in an essay titled “Regrets on Parting with My Old Dressing Gown,” where he famously noted, “I was absolute master of my old gown, but I have become a slave to my new one.”
The Essentials of Modern Consumption
While you might not be buying silk dressing gowns, the Diderot Effect is more prevalent today than ever before. It thrives on our desire for internal consistency—the psychological need to ensure that our environment and our possessions “fit” together to project a specific identity.
- The Tech Ecosystem Trap: Buying a new smartphone often leads to purchasing specific cases, wireless earbuds, a smartwatch, and eventually upgraded cloud storage subscriptions to handle the new device’s high-resolution photos.
- The Fitness Spiral: Joining a boutique gym often triggers the “need” for high-end athletic wear, specialized shoes, heart-rate monitors, and specialized supplements.
- Home Improvement Cascades: Installing new kitchen countertops often makes the old appliances look dated, leading to a full suite of stainless steel upgrades and new cabinetry.
According to data from the Bureau of Labor Statistics (BLS), American households spend a significant portion of their income on “miscellaneous” goods and services that fall outside of essential housing and food. Much of this spending is driven by the desire to maintain a cohesive lifestyle, often fueled by the psychological pressure to upgrade everything simultaneously.
How the Psychology of Spending Betrays Your Budget
The Diderot Effect is powerful because it leverages two primary human tendencies: our need for identity and our tendency toward “lifestyle creep.” When you buy something new that represents a “better” version of yourself, your existing items become symbols of your “former” self. This creates cognitive dissonance—a mental discomfort that you resolve by spending more money to align your environment with your new identity.
Marketers understand this perfectly. They don’t just sell you a product; they sell you a lifestyle. When you see an advertisement for a luxury SUV, you aren’t just seeing a car; you are seeing a person with a specific wardrobe, specific hobbies, and a specific home. Once you buy the car, the Diderot Effect kicks in, nudging you to acquire the rest of that curated life.
“Beware of little expenses; a small leak will sink a great ship.” — Benjamin Franklin, Statesman and Author
Reactive vs. Intentional Spending
To master your money mindset, you must distinguish between purchases that serve a functional purpose and those that serve the Diderot Effect. The following table illustrates the difference between these two spending behaviors:
| Feature | Intentional Spending | The Diderot Spiral (Reactive) |
|---|---|---|
| Primary Trigger | Functional need or planned goal. | Reaction to a previous purchase. |
| Effect on Environment | Integrates with what you already own. | Makes current items feel inadequate. |
| Financial Impact | Budgeted and predictable. | Unplanned and compounding. |
| Post-Purchase Feeling | Contentment and utility. | Urgency to buy the “next” thing. |
Strategies to Break the Cycle
You cannot simply “will” your way out of the Diderot Effect because it is a deeply ingrained psychological response. Instead, you must build systems that protect your bank account from your brain’s impulses. Implement these actionable strategies to regain control over your spending habits.
1. Implement the “One-In, One-Out” Rule
Every time you bring a new item into your home, you must donate, sell, or discard an old one. This creates a natural friction for new purchases. If you buy a new pair of shoes, you must give away an old pair. This forces you to evaluate if the new item is truly better than what you already possess, rather than simply adding to a growing mountain of “stuff.”
2. Practice the 30-Day Cooling-Off Period
When you feel the urge to buy something that completes a set or upgrades your lifestyle, wait 30 days. Most Diderot-driven impulses fade once the “newness” of the initial purchase wears off. If you still feel the need for the item after a month, you can then evaluate it as a standalone purchase rather than a reactive one.
3. Stop Looking for “Sets”
Modern retail is designed to show you items in “vignettes.” Furniture stores set up entire rooms; clothing retailers show you “complete looks.” Resist this. When shopping, view every item in isolation. Ask yourself: “Does this item serve a purpose on its own, regardless of whether it matches my other things perfectly?”
4. Avoid the “Starting Over” Fallacy
We often tell ourselves that it’s cheaper to replace everything at once to “get it over with.” This is rarely true. Embrace the eclectic nature of your current belongings. High-quality personal finance requires a level of comfort with imperfection. Your home doesn’t need to look like a showroom; it needs to be a functional space that supports your long-term financial health.
5. Review Your Exposure
Your environment dictates your desires. If you spend your evenings scrolling through social media influencers who showcase “restock” videos or home makeovers, you are constantly triggering the Diderot Effect. Curate your digital environment. Unsubscribe from marketing emails that suggest “complementary products” based on your recent orders.
Avoiding Common Errors
Even if you understand the theory, it is easy to fall into these common traps that prolong the spending spiral:
- The “Free” Trap: Accepting a high-end item for free (like a hand-me-down luxury appliance) can actually cost you more in the long run if it triggers a need to upgrade everything around it.
- Focusing on Monthly Payments: When the Diderot Effect takes hold, you might be tempted to use “Buy Now, Pay Later” services to fund the entire set. This obscures the true cost of the consumption spiral. Always look at the total price, not the monthly installment.
- Ignoring Maintenance Costs: Upgraded items often come with upgraded maintenance requirements. A high-end car requires premium fuel; a designer rug requires professional cleaning. Factor these “hidden” Diderot costs into your decision.
When DIY Isn’t Enough
For most people, awareness of the Diderot Effect is enough to curb impulsive spending. However, there are times when your spending habits might indicate a deeper financial or psychological issue. Consider seeking professional guidance in the following scenarios:
- Unmanageable Debt: If your “lifestyle upgrades” have led to credit card debt you cannot pay off within three months, contact the National Foundation for Credit Counseling (NFCC) for a structured repayment plan.
- Compulsive Spending: If you find that you cannot stop the spiral even when you want to, or if spending is causing significant stress in your relationships, a financial therapist can help you address the underlying triggers.
- Complex Financial Intersections: When your spending habits interfere with your ability to save for retirement or children’s education, consulting a Certified Financial Planner (CFP) can help you realign your daily habits with your long-term goals.
The Long-Term Financial Impact
While one or two extra purchases might seem insignificant, the cumulative effect of the Diderot Effect over a lifetime can be staggering. If you spend an extra $2,000 a year on “unintended upgrades,” and instead invested that money in a diversified portfolio with a 7% annual return, you would have nearly $200,000 more after 30 years.
The Consumer Financial Protection Bureau (CFPB) offers resources on how to build savings habits that protect you from these types of psychological drains. By recognizing that your desire for a “complete set” is just a trick of the mind, you can redirect that capital toward true financial independence.
Frequently Asked Questions
Is the Diderot Effect always bad?
Not necessarily. It can be a positive force if it motivates you to improve your health or environment in a planned, sustainable way. The danger lies in the *unplanned* and *compulsive* nature of the spending it usually triggers. If you plan an upgrade and budget for the entire “set” over time, you are in control. If the purchases happen as a reaction to a single item, the Diderot Effect is in control.
How can I talk to my partner about the Diderot Effect?
Financial friction often occurs when one person is caught in a consumption spiral while the other is trying to save. Instead of criticizing the individual purchases, discuss the *concept* of the Diderot Effect. Use it as a framework to evaluate future buys together. Asking, “Is this a Diderot purchase?” can become a neutral, judgment-free way to check each other’s spending impulses.
Does the Diderot Effect apply to digital goods?
Yes. We see this in software ecosystems (buying a Mac, then needing the specialized software, then the peripherals) and even in video games where buying a “skin” or character leads to buying additional cosmetic items to complete the look. The psychology remains the same: the desire for a cohesive identity within a specific environment.
Taking Control of Your Money Mindset
The goal of understanding the Diderot Effect is not to stop buying things altogether. It is about becoming an intentional consumer who understands why the urge to spend occurs. You have the power to break the chain of consumption by simply recognizing the first link. The next time you buy something new and feel that familiar itch to replace the “mismatched” items around it, take a deep breath. Acknowledge the Diderot Effect for what it is—a psychological quirk—and choose to be the master of your possessions rather than their servant.
Focus on the utility and joy your current items provide. By practicing gratitude for what you already have, you diminish the power of the “new” to make the “old” look inadequate. Your bank account, and your future self, will thank you for the restraint.
This is educational content based on general financial principles. Individual results vary based on your situation. Always verify current tax laws and regulations with official sources like the IRS or CFPB.
Last updated: February 2026. Financial regulations and rates change frequently—verify current details with official sources.
Leave a Reply